National Risk Management and Associates

  • Quote
  • Contact
  • Payment
  • Claims
  • Home
  • About
  • Personal
    • Wedding Insurance
    • Special Events Insurance
  • Business
  • Life and Health
  • Our Carriers
  • Resources
  • Blog

October 26, 2026 By Cendra Ray

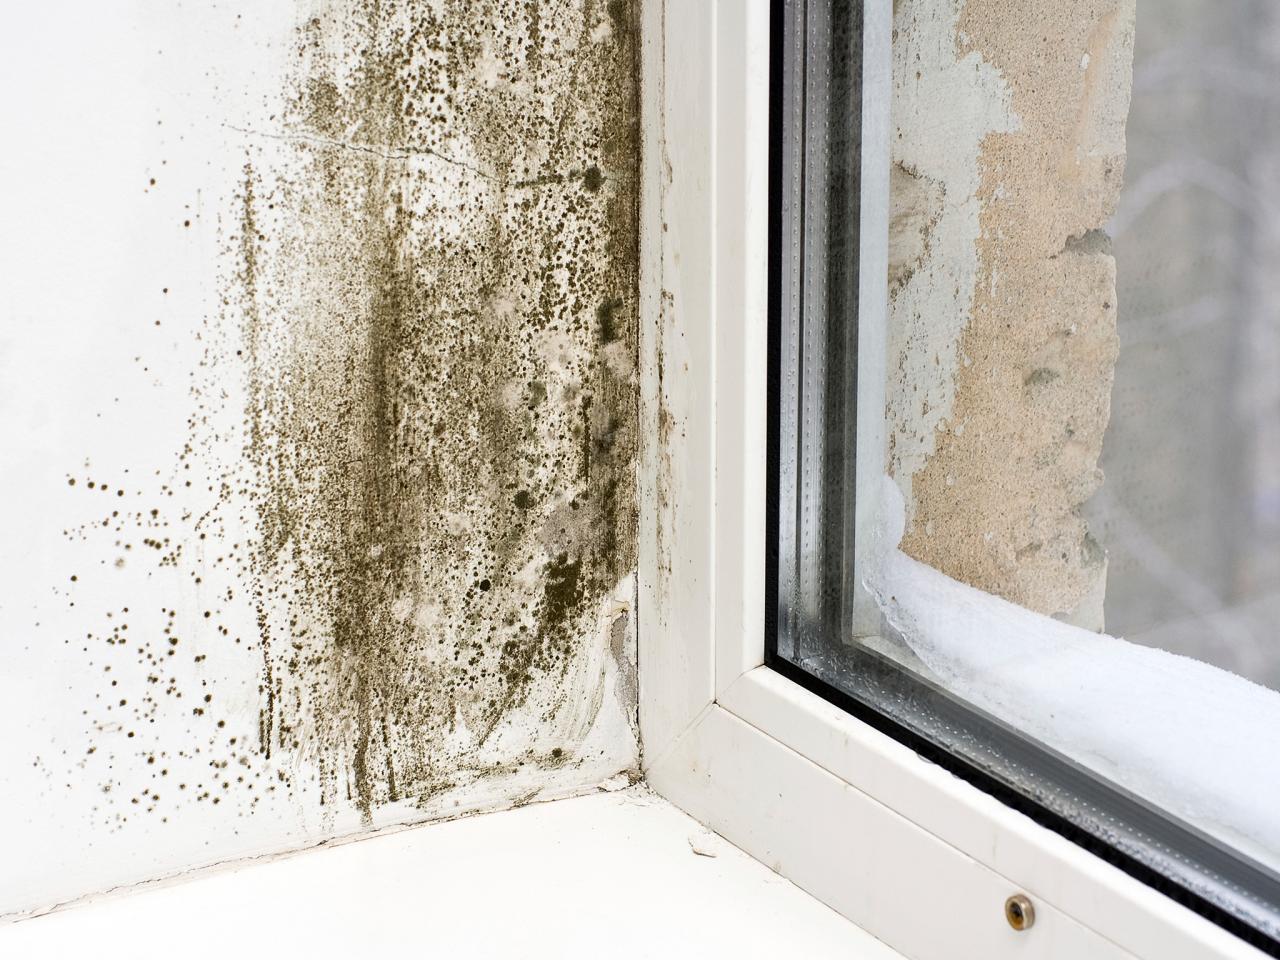
Water Damage & Mold

Mold DamageCourtesy of iii.org

Returning to your home after a flood is a big part of getting your life back to normal. But consumers and small businesses may be facing a new challenge: mold. What can you do to get rid of it? How do you get the mold out of your home or office and stay safe at the same time? CDC has investigated floods, mold, and cleanup, and offers practical tips for homeowners and others on how to safely and efficiently remove mold from the home.

In 2005, thousands of people along the Gulf Coast were faced with cleaning up mold from their homes after Hurricanes Katrina and Rita. One of our first concerns was to let homeowners and others know how they could clean up mold safely. After Hurricane Sandy in 2012, we teamed up with other federal agencies to provide practical advice on mold cleanup. This guidance outlines what to do before and after going into a moldy building, how to decide if you can do the cleanup yourself or need to hire someone, and how you can do the cleanup safely.

Prepare To Clean Up

Before you start any cleanup work, call your insurance company and take pictures of the home and your belongings. Throw away, or at least move outside, anything that was wet with flood water and can’t be cleaned and dried completely within 24 to 48 hours. Remember, drying your home and removing water-damaged items is the most important step to prevent mold damage.

Protect Yourself

We offer specific recommendations for different groups of people and different cleanup activities. This guidance educates people about the type of protection (think: gloves, goggles, masks) you need for different parts of your mold cleanup. It also identifies groups of people who should and should not be doing cleanup activities.

Be Safe With Bleach

Many people use bleach to clean up mold. If you decide to use bleach, use it safely by wearing gloves, a mask, and goggles to protect yourself. Remember these four tips to stay safe:

  • NEVER mix bleach with ammonia or any other cleaning product.
  • ALWAYS open windows and doors when using bleach, to let fumes escape.
  • NEVER use bleach straight from the bottle to clean surfaces. Use no more than 1 cup of bleach per 1 gallon of water when you’re cleaning up mold.  If you are using stronger, professional strength bleach use less than 1 cup of bleach per gallon of water.
  • ALWAYS protect your mouth, nose, skin, and eyes against both mold and bleach with an N-95 mask, gloves, and goggles.  You can buy an N-95 mask at home improvement and hardware stores.

You can take steps to keep yourself and others protected while cleaning up mold after a flood. Make sure to follow CDC’s recommendations so you can return home safely.

Resources
  • Homeowner’s and Renter’s Guide to Mold Cleanup After Disasters
  • Population Specific Recommendations for Protection From Exposure to Mold
  • Basic Facts About Molds in the Environment
  • Cleanup and Remediation

Filed Under: Insurance, Insurance News

October 19, 2026 By Cendra Ray

Rent Without Wasting Money

Courtesy of iii.org

There are more options for renting a car than ever before—bricks-and-mortar, peer-to-peer and membership-based car sharing services. While this means more choice for renters, it also creates more questions about insurance coverage. Use these tips to properly insure yourself when renting a car, and avoid wasting money on duplicative coverage.


If you’re looking to rent a car, depending on your needs and location, there are a number of alternatives—the traditional brick-and-mortar companies, peer-to-peer car services and car sharing programs—each with its own insurance parameters. It pays to understand your existing coverage first, and then look at your rental insurance options.

No matter what company or what kind of company you’re renting from, the most important step is to read and understand the car rental or car sharing agreement. Most companies clearly state what is covered as well as the supplemental coverage that can be purchased. If you don’t understand, have the rental or car sharing company representative walk you through.

If you’re renting a car, check your own coverages first

Before you enter an agreement with any type of rental service, maximize use of the insurance you’re already paying for and avoid paying for duplicate insurance.

If you own or lease a car and/or have homeowners insurance, call your insurer to first check the following:

  • How much coverage you currently have on your own car – In most cases, whatever auto insurance and deductibles you have on your own car would apply when you rent a car (providing you are using the rental car for recreation and not for business).
  • If you still have collision or comprehensive – If you dropped these coverages on your own car as a way to save money on your car insurance, you may not be covered if your rental car is stolen or damaged. Insurance rules vary by state, so it is best to check with your insurance professional for the specifics of your policy.
  • If you are covered for administrative fees, loss of use or towing charges – Check to see whether your insurance company pays for—or provides a rider for—additional fees.
  • Whether your homeowners or renters insurance covers the loss of possessions – These policies (not your car insurance) generally cover your belongings if they are damaged or stolen out of your vehicle.

The credit card you use to rent a car may also provide some insurance. Though coverage is likely to be limited—for example, it may only cover the deductible if you make a claim—it’s worth knowing what protections it will provide.

  • Know that benefits differ – Insurance coverage can depend on the company or bank that issues the card or even the level of card. For example, a platinum card may offer more robust coverage than a green card. If you have more than one card, you may want to compare what insurance they offer for car renters.
  • Contact the credit card issuer to find out what they cover – If you are depending on a credit card for insurance protection, ask the company or bank that issued the card to send you their coverage information in writing.
  • Credit card insurance benefits are usually secondary – That is, they will kick in after your personal insurance policy or the insurance coverage offered by the rental car company are utilized.

Insurance if you’re renting from a brick-and-mortar car rental

Brick-and-mortar car rental companies are generally found at airports, train stations or other locations where travelers converge. These traditional rental companies allow you to simply reserve or select a vehicle from one of the many generally available on any given day. The insurance you’ll be offered is fairly standard (though, like all car insurance, it varies by state).

Depending on what type of auto and/or homeowners insurance you carry, you may want to consider some of the insurance coverage provided by the rental car company. While auto insurance regulations, costs and coverage will vary by state and insurer, consumers renting from traditional companies can generally choose from the following coverages:

  • Loss Damage Waiver (LDW) – Also referred to as a collision damage waiver, an LDW is not technically an insurance product—it is designed to relieve or “waive” renters of financial responsibility if their rental car is damaged or stolen. Waivers may also provide coverage for “loss of use,” in the event the rental car company charges for the time a damaged car cannot be used because it is being fixed, as well as towing and administrative fees. The LDW may become void if the accident was caused by speeding, driving on unpaved roads or driving while intoxicated. However, if you carry comprehensive and collision auto insurance, you may already be covered for damage to a rental car.
  • Liability Insurance – By law, rental companies must provide the state required minimum amount of liability insurance coverage—often this does not provide enough protection. If you carry your own auto insurance and have opted for higher liability limits (which is recommended), you’ll be adequately covered. Non car-owners who are frequent renters have the option of purchasing a non-owner liability policy, which can provide the additional liability needed.
  • Personal accident insurance – This covers the driver and passengers for medical and ambulance bills for injuries caused in a car crash. Whether or not you should consider this depends on your health insurance and the personal injury protection (PIP) provided by your auto insurance, which will likely cover medical expenses.
  • Personal effects coverage–This provides insurance protection for the theft of items from a rental car. Consider this if you do not carry homeowners or renters insurance to cover this type of loss.

Insurance if you’re using a car sharing service

With car sharing programs, for a monthly or annual membership fee, consumers can pick up a vehicle at a wide range of locations for periods ranging from minutes to days. These programs are popular in urban settings where owning a car can be expensive or difficult, but where it’s convenient have a car available when it’s needed. Coverage options vary widely, but there is usually some insurance included.

The insurance offered by these types of companies is not standardized so read the insurance coverage information carefully (it can usually be found on the service’s website). If you have any questions, call the company’s customer service line. And contact your auto insurer if you feel you need more information to make an educated insurance coverage decision.

  • Car sharing programs (like ZipCar) generally include insurance costs in the fee. However, if the car is involved in a collision or is stolen, the renter may be billed for a specific dollar amount that is stated in the membership agreement. For an additional cost, customers can purchase a “waiver” to avoid paying the accident fee.
  • Many car sharing programs limit coverage for young drivers to the minimum state required amount of liability. Renters under the age 21 should read the insurance coverage carefully. If it’s not adequate to their needs, they can look into whether their parents’ auto insurance would cover them for the difference, or purchasing their own non-owner liability policy.

Insurance if you’re renting from a peer-to-peer service

Peer-to-peer car rental networks enable consumers to rent personally owned cars from others. Insurance coverage varies widely, depending on location and service.

  • Peer-to-peer rental services (like Turo) may offer a range of insurance options and, under some circumstances, the driver may decline coverage.


Next steps: When considering these options for your rental car, it helps to have a general understanding of your auto insurance coverage.

Filed Under: Car Insurance, Insurance, Insurance News

October 12, 2026 By Cendra Ray

What is Business Interruption Insurance?

Business Interruption InsuranceCourtesy of iii.org

Business interruption insurance can be as vital to your survival as a business as fire insurance. Most people would never consider opening a business without buying insurance to cover damage due to fire and windstorms. But too many small business owners fail to think about how they would manage if a fire or other disaster damaged their business premises so that they were temporarily unusable. Business interruption coverage is not sold separately. It is added to a property insurance policy or included in a package policy.

A business that has to close down completely while the premises are being repaired may lose out to competitors. A quick resumption of business after a disaster is essential.

  1. Business interruption insurance compensates you for lost income if your company has to vacate the premises due to disaster-related damage that is covered under your property insurance policy, such as a fire. Business interruption insurance covers the revenue you would have earned, based on your financial records, had the disaster not occurred. The policy also covers operating expenses, like electricity, that continue even though business activities have come to a temporary halt.
  2. Make sure the policy limits are sufficient to cover your company for more than a few days. After a major disaster, it can take more time than many people anticipate to get the business back on track. There is generally a 48-hour waiting period before business interruption coverage kicks in.
  3. The price of the policy is related to the risk of a fire or other disaster damaging your premises. All other things being equal, the price would probably be higher for a restaurant than a real estate agency, for example, because of the greater risk of fire. Also, a real estate agency can more easily operate out of another location.

Extra expense insurance

Extra expense insurance reimburses your company for a reasonable sum of money that it spends, over and above normal operating expenses, to avoid having to shut down during the restoration period. Usually, extra expenses will be paid if they help to decrease business interruption costs. In some instances, extra expense insurance alone may provide sufficient coverage, without the purchase of business interruption insurance.

Filed Under: Insurance, Insurance News

October 6, 2026 By Cendra Ray

Renter’s Insurance-A Guide

Renters InsuranceCourtesy of iii.org

If you rent a house or apartment and experience a fire or other disaster, your landlord’s insurance will only cover the costs of repairing the building. To financially protect yourself you will need to buy renters or tenants insurance.


Renters insurance protections

Like homeowners insurance, renters insurance includes three key types of financial protection:

  • Coverage for personal possessions
  • Liability protection
  • Additional living expenses (ALE)

The big difference is that renters insurance doesn’t cover the building or structure of the apartment—that’s the landlord’s responsibility.

The following questions will help you choose the right coverage when you are shopping around for renters insurance or discussing your needs with an insurance professional.

Coverage for personal possessions

Coverage for your personal property is a key component of renters coverage, protecting you from theft, fire and a host of other unfortunate events.

1. How much insurance should I buy?

Make sure you have enough insurance to replace all of your personal possessions in the event of a burglary, fire or other covered disaster. The easiest way to determine the value of all your personal possessions is to create a home inventory—a detailed list of all of your belongings along with their estimated value.

2. Should I choose replacement cost or actual cash value coverage?

Actual cash value policies include a deduction for depreciation (that is, the idea that items lose value over time). Replacement cost coverage is pricier but can be well worth the extra expense if your belongings are damaged or destroyed (think about how much you’d get for your TV used versus how much it would actually cost to replace).

3. What disasters are—and are not—covered?

Renters insurance covers you against losses from fire or smoke, lightning, vandalism, theft, explosion, windstorm and certain types of water damage (such as from a burst pipe or when the tenant upstairs leaves the water running in the bathtub and floods your apartment).

Like standard homeowners policies, most renters insurance policies do not cover floods or earthquakes. Flood coverage is available from the National Flood Insurance Program and a few private insurers. You can get earthquake insurance as a separate policy or have it added as an endorsement to your renters policy, depending on where you live.

4. What is my deductible, and how does it work?

A deductible is an amount of money you responsible for paying before your insurance coverage. For example, if you have a $500 deductible and a fire destroys $5000 worth of furniture, the first $500 is your responsibility and your insurance company will cover $4500.

Renters insurance deductibles are generally specified as a dollar amount, which can be found on the Declarations page of your policy. In general, the larger the deductible, the lower your insurance premium.

5. What is a “floater” and do I need one?

A floater is a separate policy that provides additional coverage for more costly valuables if they are lost or stolen. If you have expensive jewelry, furs, collectibles, sports equipment or musical instruments, consider adding a floater to your policy to protect against their loss.

6. Am I covered if I am traveling or away from home?

Most renters polices include what is called off-premises coverage, which means belongings that are outside of your home are covered against the same disasters listed in your policy. For example, property stolen from your car or a hotel room while you’re traveling would be protected.

Liability protection

7. What is liability insurance?

Renters insurance provides liability protection that covers you against lawsuits for bodily injury or property damage done by you, your family members and even your pets. This coverage pays for the cost of defending you in court, up to the limit of your policy.

Your renters policy should also include no-fault medical coverage as part of the liability protection. Medical payments coverage allows someone who gets injured on your property to simply submit his or her medical bills directly to your insurance company so the bills can be paid without resorting to a lawsuit.

8. Do I have enough liability insurance?

Make sure the amount of liability coverage provided by your policy is sufficient to protect your financial and other material assets in the event of a lawsuit.

9. Do I need an umbrella liability policy?

If you need a larger amount of liability protection, consider purchasing a personal umbrella liability policy. An umbrella policy kicks in when you reach the limit on the underlying liability coverage provided by your renters or auto policy. It will also cover you for things such as libel and slander.

Additional living expenses

Additional living expenses (ALE) coverage provides coverage if your home is destroyed by an insured disaster and you need to live elsewhere for a time.

9. What does ALE cover?

The additional living expenses portion of your rental insurance policy pays for hotel bills, temporary rentals, restaurant meals and other expenses you incur while your rental home is being repaired or rebuilt. Essentially, it covers the expenses you would not have to incur if you had your usual roof over your head.

10. How much does ALE cover?

Most policies will reimburse you the full difference between your additional living expenses and your normal living expenses; however, there are generally limits as to the total amount the insurer will pay or time limits specifying how long you’re eligible for the ALE payments. Make sure you’re comfortable with the limits of the policy you choose.

Multiple policy and other discounts

10. What types of discounts are offered on renters insurance?

Insurance companies often offer discounts on renters insurance if you have another policy with them—for example, car insurance or business insurance.

You may also get a discount if you:

  • Have a security system
  • Use smoke detectors
  • Use deadbolt locks
  • Have good credit
  • Stay with the same insurer
  • Are over 55 years old

Discounts may vary widely by insurance company and by state, so review your options carefully. As always, the same rule-of-thumb applies: shop around for the best deal.

Filed Under: Insurance, Insurance News

October 1, 2026 By Cendra Ray

Saving the Cost of Repairing Water Damage

Water DamageCourtesy of iii.org

Pop quiz: what’s one of the most common types of homeowners insurance claims? (Hint: it’s not fire.)

It’s water damage. Maybe that’s not surprising – it rains a lot in many places. But what may surprise you is that things like pipe bursts and broken appliances are increasingly the main causes of water damage in homes.

In insurance-speak, these are called “non-weather water damage claims.” Worryingly, these claims are happening more often and are getting a lot more expensive. A Best’s Review article reports that the average homeowners water damage claim is now over $6,700. Large losses (over $500,000) have doubled in number over the past three years. Non-weather water damage is now costing insurers (and their policyholders) billions in losses every year.

This is happening for several reasons. Our housing stock is aging, as is our infrastructure. More houses are being built and they’re getting bigger – many houses now have extra bathrooms and second-floor laundry rooms, which means more piping. (The story is probably different in Florida. You can read why that is here.)

But the worst part is that many – if not most – water damage claims are preventable. Inspecting pipes or conducting routine maintenance can go a long way. That’s where the internet of things (IoT) comes in. Smart devices and connected sensors installed on piping can detect leaks before they occur or before they cause too much damage. They’re basically smoke detectors, but for water.

And they work. Best’s Review noted that installing IoT devices can reduce water losses by up to 93 percent.

The Review quoted an IoT company CEO who claimed that leak detection devices could save insurers and their customers $10 billion every year.

Homeowners have admittedly been slow to install IoT to help detect leaks. But insurers are hopeful that raising awareness about the issue, offering policyholder incentives like premium discounts, and encouraging IoT installation during home construction will begin to turn the tide.

Update: Of interest, Washington state adopted a rule in 2018 that specifically mentions water monitors and water shut-off systems as permissible tools for an insurer’s risk reduction program.

Filed Under: Insurance, Insurance News

  • 1
  • 2
  • 3
  • …
  • 39
  • Next Page »

Quick Contact

(407) 767-2950

Business Hours

Monday – Friday: 9 AM- 5 PM


  • Privacy Policy
  • Accessibility statement

24 Hour Hotline: (407) 415-8528

National Risk Management & Associates
220 Magnolia Avenue
Sanford, FL 32771
Phone: (407) 767-2950


Designed by iWebResults

Copyright 2026 National Risk Management, All Rights reserved